California Home Sales Are Slowing: What the September 2026 Numbers Mean for Buyers
California home sales fell 9.1% year over year in September 2026. Here is what the data shows for Southern California and what it means if you are buying or selling.
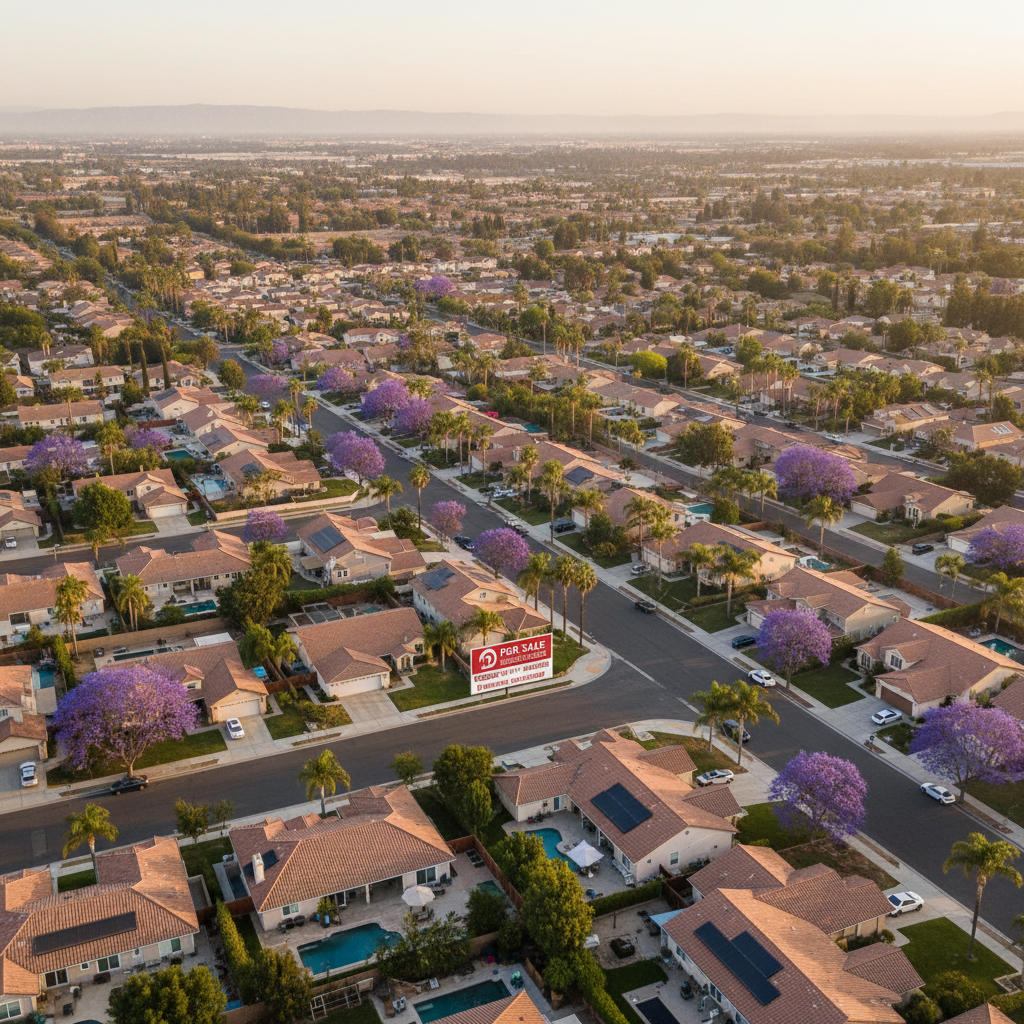
The California Association of Realtors released its September 2026 home sales report on October 19, and the headline number is a 9.1% year-over-year decline in existing single-family home sales statewide. That is a meaningful drop, and it reflects conditions that buyers and sellers across Southern California are experiencing firsthand.
Here is what the data shows, what it means in practical terms, and what buyers should understand before drawing conclusions.
What the September Numbers Show
According to C.A.R.'s October 19, 2026 report, California existing single-family home sales fell 9.1% compared to September 2025 on a seasonally adjusted annualized rate basis. This follows a pattern of elevated rates continuing to suppress transaction volume across the state.
Median home prices statewide remained elevated, reflecting the persistent imbalance between limited inventory and underlying demand — even as the number of transactions declined.
Important distinction: A decline in sales volume is not the same as a decline in home values. Fewer homes changing hands does not mean prices are falling. In California's supply-constrained market, prices have remained resilient even as transaction counts have dropped. Buyers should not interpret a sales slowdown as a signal that prices are about to collapse.
Southern California Regional Picture
The regional data within the C.A.R. report shows variation across Southern California counties:
Orange County remains one of the most expensive and supply-constrained markets in the state. Median prices in Orange County have held near or above $1.2 million for much of 2026. Sales volume has declined, but the limited inventory of homes for sale continues to support prices. Buyers in Orange County are competing for a smaller pool of available homes.
Los Angeles County has seen similar dynamics — elevated prices, reduced transaction volume, and persistent affordability challenges for first-time buyers. The county's size and diversity mean conditions vary significantly by submarket.
San Diego County has maintained strong price levels, supported by limited land availability, strong employment, and continued demand from military and tech sector buyers. The conforming loan limit for San Diego County in 2026 is $1,104,000, which means a significant portion of the market falls within conforming loan territory.
Riverside and San Bernardino Counties have historically offered more affordability relative to coastal markets, and that relative affordability continues to attract buyers priced out of Orange County and Los Angeles. The 2026 conforming loan limit for Riverside and San Bernardino Counties is $832,750.
What Is Driving the Slowdown
The primary driver of reduced sales volume is affordability pressure from elevated mortgage rates. When rates rise, monthly payments increase for the same purchase price, which reduces the pool of buyers who can qualify and afford to buy. Sellers who locked in low rates in prior years are also reluctant to sell — the "lock-in effect" discussed in our article on whether to give up a low mortgage rate to move is reducing the supply of homes coming to market.
The result is a market with both reduced demand (fewer buyers who can afford current prices at current rates) and reduced supply (fewer sellers willing to give up low existing rates). This combination tends to suppress transaction volume while keeping prices relatively stable.
What This Means for Buyers
A slower market is not necessarily a bad market for buyers. Here is what the current conditions mean practically:
More time to make decisions. When sales volume is lower and homes are sitting on the market longer, buyers have more time to conduct due diligence, negotiate, and make thoughtful decisions. The frantic pace of the 2021–2022 market — where homes received dozens of offers within days — has moderated in most Southern California submarkets.
More negotiating room in some segments. In price ranges and property types where inventory has built up, buyers may have more leverage to negotiate on price, seller concessions, or repairs. This varies significantly by location and price point.
Seller concessions are more available. In a slower market, sellers are more likely to offer concessions — contributions toward closing costs, rate buydowns, or repairs — that were rare during the peak seller's market. These concessions can meaningfully reduce a buyer's cash to close or monthly payment.
Prices have not collapsed. Buyers waiting for a significant price correction in Southern California's supply-constrained coastal markets have been waiting for years. The structural factors that support California home prices — limited land, strong employment, population density, and restrictive zoning — have not changed. A slowdown in sales volume does not guarantee a price correction.
What This Means for the Mortgage Market
Reduced sales volume means fewer purchase mortgage originations, which puts competitive pressure on lenders. In a slower purchase market, lenders compete more aggressively for the transactions that do occur. This can translate to more competitive pricing, more willingness to work with borrowers on rate and fee structures, and more attention to service.
For buyers who are ready to purchase, the current environment — slower market, more negotiating room, competitive lender pricing — is in some ways more favorable than the peak seller's market, even with higher rates.
The Conforming Loan Limit Context
For buyers in Southern California, understanding the conforming loan limits for your county matters for financing strategy. Loans at or below the conforming limit qualify for conventional financing with standard pricing. Loans above the limit require jumbo financing, which has different qualification requirements and pricing.
The 2026 conforming loan limits for key Southern California counties:
- Orange County and Los Angeles County: $1,249,125
- San Diego County: $1,104,000
- Riverside County and San Bernardino County: $832,750
If your purchase price puts your loan amount near or above these limits, your financing options and qualification requirements are different from a standard conforming loan. See our article on jumbo loans in San Diego for more on how jumbo financing works.
The Bottom Line
California home sales are slower in 2026 than they were a year ago, driven primarily by affordability pressure from elevated mortgage rates and the lock-in effect keeping potential sellers in place. This has reduced transaction volume without producing the price collapse some buyers have been waiting for.
For buyers who are financially ready, the current market offers more time, more negotiating room, and more seller concessions than the peak seller's market. For buyers who are not yet ready, the most productive use of time is strengthening your financial position — credit, savings, and debt-to-income ratio — so you are prepared when the right home and the right opportunity align.
If you want to understand your financing options in the current Southern California market, contact us or schedule a call.
NMLS Individual #1087365 · NMLS Company #1147207 · CA DRE #01265685. SMS Mortgage is a licensed mortgage broker in California and Colorado. Stephanie Pedley holds individual MLO authorizations in Texas through B Walters CO., LLC (NMLS #262157), Ohio through Beacon of Hope Residential LLC (NMLS #2543671), and Nevada through CASMIA HOLDING LLC (NMLS #1740673). Not a commitment to lend. All loans subject to credit approval.
Explore Topics
Written by
Stephanie Pedley
Mortgage professional and real estate broker with 34+ years of experience in lending, underwriting, and loan strategy. SMS Mortgage is licensed in California and Colorado. Stephanie Pedley holds individual MLO authorizations in Texas, Ohio, and Nevada through sponsorship arrangements. NMLS Individual #1087365 · NMLS Company #1147207 · CA DRE #01265685.