Can an HOA Special Assessment Affect Your Condo Mortgage Approval? What Orange County Buyers Need to Know
Buying an Orange County condo? Learn how HOA special assessments, major repairs, reserves and insurance can affect condo mortgage financing.
Imagine finding the Orange County condo you want, getting your offer accepted and feeling confident about your financing.
Your credit is good. Your income qualifies. You have the funds to close.
Then your lender starts reviewing the homeowners association.
That is where some condo buyers are surprised to learn an important fact:
With a condominium, qualifying the borrower may only be part of the mortgage approval process. The condominium project itself may also need to meet the requirements of the loan program.
A recent San Clemente story is a good example of why this matters.
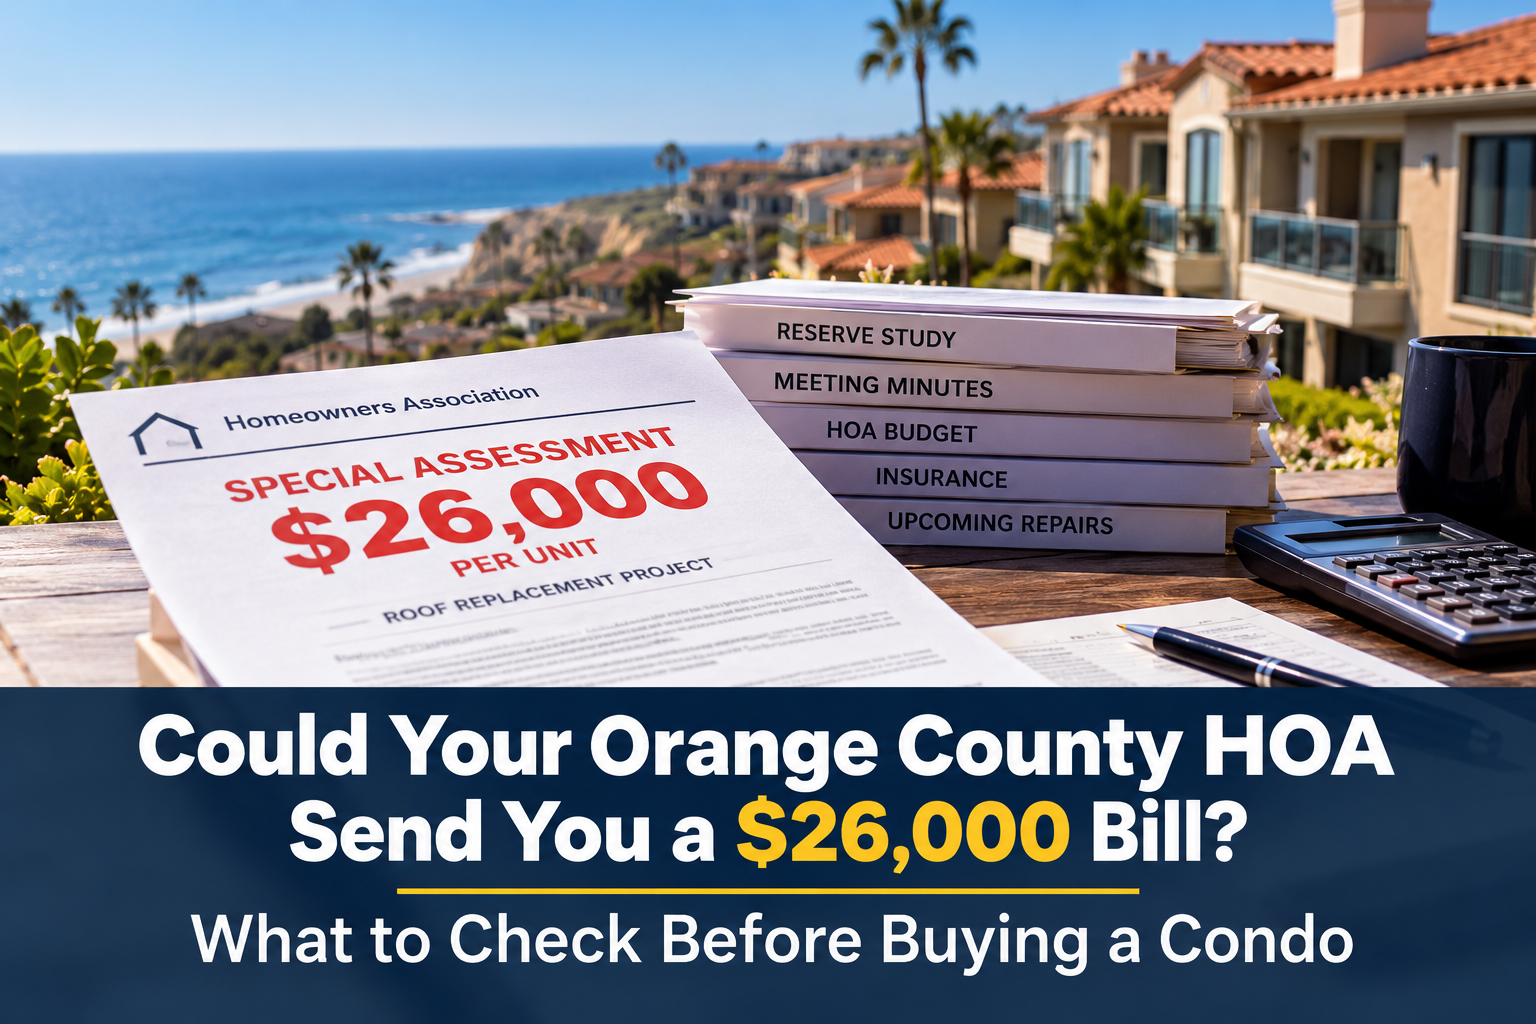
ABC7 reported on September 1, 2026, that homeowners at the Villa Moura condominium community were challenging an emergency roof assessment of more than $26,000 per unit. Residents interviewed by ABC7 questioned whether the assessment should have been treated as an emergency and described the financial strain it could cause. The HOA board declined comment because of ongoing legal matters, and the homeowners' allegations have not been established as legal findings.
Whether that particular assessment is legally appropriate is a matter specific to that association.
But from a mortgage perspective, it raises an entirely different question:
What happens when a condo association has a large assessment, significant repairs or financial concerns while you are trying to finance a unit in the project?
The answer is: it depends.
A special assessment does not automatically mean a condo cannot be financed. But it can trigger questions that need to be answered before the lender can determine whether the project meets the requirements of the particular mortgage program.
Condo Financing Is Different From Financing a Single-Family Home
When you buy a traditional single-family home, the lender primarily evaluates you and the property securing the loan.
With a condominium, there can be another layer.
Depending on the loan type and transaction, the lender may need to evaluate the condominium association and project.
Fannie Mae's project standards specifically recognize that characteristics of the overall project can affect mortgages secured by individual condo units, and lenders must determine whether applicable project requirements are satisfied.
That means I may be looking at more than:
- your credit
- income
- assets
- down payment
- appraisal
- debt-to-income ratio
There may also be questions about:
- HOA finances
- reserve funding
- special assessments
- major repairs
- deferred maintenance
- master insurance
- litigation
- structural or mechanical concerns
- owner assessment delinquencies
- other project-level issues
The exact review depends on the loan program, project and transaction.
Does a Special Assessment Automatically Kill the Loan?
No.
This is one of the most important points for buyers to understand.
An HOA having a special assessment does not, by itself, mean the condo is unfinanceable.
The lender may need to determine things such as:
- Why was the assessment imposed?
- What work is being performed?
- Is the work related to ordinary improvements or necessary repairs?
- Are there safety or structural issues?
- Has the work begun?
- How will the project be funded?
- Are homeowners paying the assessment?
- Are there significant assessment delinquencies?
- Is the association otherwise financially stable?
- Are additional assessments anticipated?
The answers matter.
An assessment for a routine planned improvement is very different from an assessment arising from significant unresolved building deterioration.
Major Repairs Can Matter More Than the Dollar Amount
A $5,000 assessment could potentially raise more financing concerns than a $25,000 assessment depending on why the money is needed.
For example, lenders are particularly concerned about certain projects with unresolved critical repairs.
Fannie Mae's current guidelines identify projects in need of certain critical repairs as potentially ineligible, with lenders responsible for evaluating applicable project documentation.
So I do not want buyers focusing only on:
"How much is the assessment?"
I also want to know:
"What problem is the assessment paying to fix?"
That distinction can be extremely important.
Deferred Maintenance Deserves Attention
One issue that can create mortgage complications is significant deferred maintenance.
A condo association may have postponed a large project for years because completing it would require increased dues or a special assessment. Eventually, that work still has to be done.
Examples might include significant:
- roofing problems
- water intrusion
- balcony or exterior deterioration
- structural repairs
- mechanical systems
- plumbing
- electrical components
- other major common-area repairs
Not every maintenance issue creates a mortgage eligibility problem. But when the issue involves safety, structural integrity or major unresolved repairs, it may require substantially more review.
HOA Reserves Matter Too
Another area lenders may review is the HOA's reserve funding.
Reserve accounts are designed to help associations prepare for major future repairs and replacements instead of relying entirely on homeowners for large unexpected assessments.
Under Fannie Mae's current Full Review standards, lenders review the HOA projected budget and replacement-reserve funding. Fannie Mae also permits an acceptable reserve study to be used in certain circumstances to demonstrate adequate reserves.
Freddie Mac similarly addresses replacement reserves and reserve-study requirements in its condominium guidance.
That doesn't mean every association needs to have enormous amounts of cash sitting in the bank. It means the financial picture of the association can be relevant to financing.
The HOA's Master Insurance Can Affect Financing
Insurance is another major piece of the condo puzzle.
With a condominium, the individual buyer usually obtains coverage for the unit as required, but the homeowners association typically carries a master insurance policy covering portions of the project.
Depending on the mortgage program, the lender may need to verify that applicable insurance requirements are satisfied.
That is why I want to identify master-policy issues early rather than discovering them several days before closing. The question is not simply:
"Does the HOA have insurance?"
The lender may need to determine whether the actual coverage meets the requirements applicable to the loan.
If you want a deeper look at how master insurance fits into the condo financing picture, I covered that topic in detail in Buying a Condo? Why the HOA's Master Insurance Policy Can Affect Your Mortgage Approval.
What About HOA Loans?
Sometimes an association borrows money to complete a large repair project rather than charging homeowners the entire cost immediately.
That is not automatically a financing problem either. But it becomes part of the HOA's overall financial picture.
For example, I may want to understand:
- Why was the loan necessary?
- What project did it fund?
- How is the association repaying it?
- Has the cost already been incorporated into homeowner dues?
- Does the association have adequate funds for other upcoming repairs?
- Are additional assessments anticipated?
FHA condominium project guidance also considers association financial records, including special assessments, loans and other financial variations, as part of applicable project analysis.
You Can Be an Excellent Borrower and Still Have a Condo Issue
This is the part I especially want buyers to understand.
You can have excellent credit, stable income, plenty of assets and a strong down payment — and the lender can still need additional information about the condominium project.
That does not mean the borrower did anything wrong. It means condo financing has two components that can intersect: the borrower and the project.
When I know early that a property is a condo, I want to identify potential project questions as soon as possible.
Questions I Want Answered Early
If I am financing an Orange County condo and there are signs of a large assessment or major HOA project, I would rather investigate early than wait until underwriting is nearly complete.
Some of the things worth identifying include:
- Is there a current special assessment?
- Has another assessment been approved but not yet billed?
- Are additional assessments being discussed?
- What is the assessment paying for?
- Are major repairs underway?
- Are repairs complete?
- Are there unresolved structural or safety concerns?
- Is there significant deferred maintenance?
- What does the HOA budget show?
- Is there a current reserve study?
- Is the HOA adequately funding reserves under the applicable loan requirements?
- Does the association have outstanding loans?
- Are homeowners delinquent on regular or special assessments?
- Is the master insurance policy adequate for the applicable loan program?
- Is there litigation involving the project?
- Are engineering or structural reports available?
Not every loan requires every one of these documents. The purpose is to identify potential financing issues before they become closing issues.
Do Not Wait Until the End of Escrow
One of the worst times to discover a condo-project problem is after your appraisal is complete, inspections are finished, loan disclosures are signed, movers are scheduled and everyone expects to close in a few days.
That is why condo buyers should tell their mortgage professional exactly what type of property they are considering as early as possible.
If there is already a disclosed special assessment, significant construction project or HOA issue, bring it up immediately.
Sometimes the answer is straightforward. Sometimes additional documents are needed. Sometimes a different loan program or project-review method may need to be considered. And sometimes a project simply may not satisfy a particular program's requirements in its current condition.
The important thing is finding that out early.
A $26,000 Assessment Is More Than an HOA Question
The San Clemente situation reported by ABC7 is receiving attention because a $26,000-plus assessment is a very large expense for an individual homeowner.
For a condo buyer, however, the story illustrates something else: the condition and finances of the HOA can intersect directly with the mortgage.
The special assessment itself is only one piece. What matters for financing can include why the assessment exists, what repairs are needed, the condition of the project, how the association is funding the work, the adequacy of reserves, insurance coverage and the requirements of the particular loan program.
That's why I don't want to wait until the end of a transaction to start asking condo questions.
If you're also looking for guidance on what to review as a buyer before making an offer in an HOA community, HOA Special Assessments: What Every California Buyer Must Know covers the due-diligence side of that picture.
Buying an Orange County Condo?
If you're considering a condo in San Clemente, Dana Point, Laguna Niguel, Laguna Hills, Lake Forest or elsewhere in Orange County, financing can involve more than simply qualifying you for the payment.
SMS Mortgage can help identify potential condo-project financing questions early so you have a clearer picture before getting too far into the transaction.
Every condominium and every loan scenario is different, and project eligibility ultimately depends on the applicable loan-program and lender requirements.
Contact Stephanie Pedley to discuss your Orange County condo purchase.
This article is for general educational purposes only and is not a commitment to lend, guarantee of approval or legal advice. Mortgage guidelines and condominium-project requirements can change, and individual loan and project circumstances vary.
Source: ABC7 Los Angeles, September 1, 2026, "San Clemente condo owners stunned by sudden $26,000 HOA fee for emergency roof assessment."
Explore Topics
Written by
Stephanie Pedley
Mortgage professional and real estate broker with 34+ years of experience in lending, underwriting, and loan strategy. Licensed in California, Colorado, Texas, and Ohio. NMLS Individual #1087365 · NMLS Company #1147207 · CA DRE #01265685.

